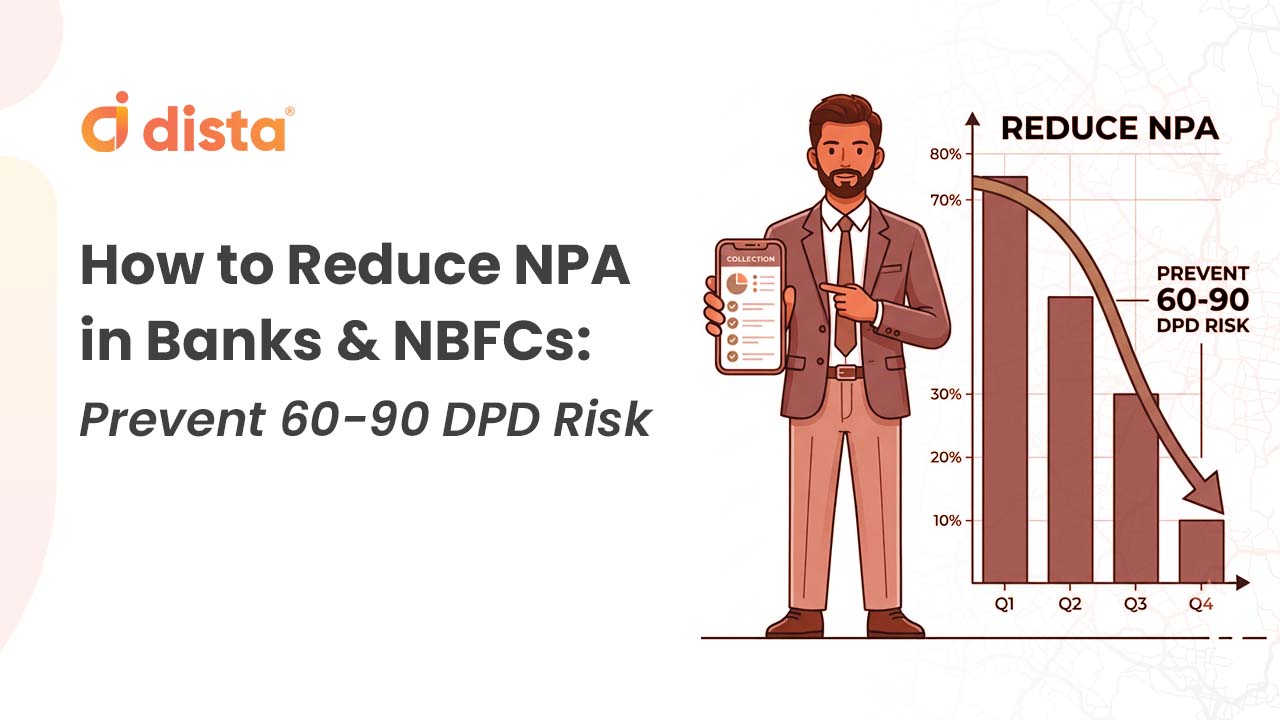
India’s lenders have come a long way. Scheduled Commercial Banks’ gross NPA ratio fell to approximately 1.73% of gross advances as of March 2026, (down from 10.4% in March 2015) a multi-decade low.
However, these numbers do not tell the full story. The actual work of NPA recovery meaning, converting stressed assets back into cash or bringing them to a stable status, remains one of the hardest operational challenges in banking and NBFC management.
Every unresolved NPA ties up capital, inflates provisioning costs, and limits a lender’s ability to deploy fresh credit. The institutions that recover faster and more efficiently gain a measurable edge over those that don’t.
Here are seven NPA recovery strategies that banks and NBFCs can put to work across their portfolios. (Source)
What Is NPA Recovery?
NPA recovery refers to the process of collecting overdue dues from borrowers whose accounts have been classified as non-performing, typically those more than 90 days past due. Recovery of NPA can take several forms: full repayment of principal and interest, a negotiated one-time settlement, asset liquidation under SARFAESI, or resolution through the Debt Recovery Tribunal.
The objective is to deploy strategies to recover some value from stressed assets before they migrate further into the loss category.
How Banks Choose the Right Recovery Route
Not every stressed account calls for the same response. The NPA recovery methods a bank or NBFC chooses depends on a combination of account characteristics, borrower profile, and the legal options available.
|
Factor
|
What It Determines
|
|---|---|
|
Loan type (secured vs. unsecured)
|
Whether SARFAESI is an option; secured loans open statutory recovery routes, unsecured loans rely on field and digital
|
|
DPD / Age of NPA
|
Urgency and track — SMA accounts get early intervention, Sub-standard gets negotiation, Doubtful/Loss triggers legal or write-off
|
|
Outstanding amount
|
Economics of the route — high-value accounts justify legal action, small-ticket accounts need low-cost digital or group recovery models
|
|
Collateral / Security
|
Strength of SARFAESI action; liquid or easily enforceable collateral accelerates recovery, disputed or depreciated assets complicate it
|
|
Borrower response
|
Responsive borrowers move to OTS or structured repayment; unresponsive or absconding borrowers escalate to legal
|
|
Past contact history
|
Informs channel selection — if field visits have failed repeatedly, digital or legal routes take priority
|
Based on these factors, NPA Classification usually places cases fall into one of three recovery tracks:
Field-first
Responsive borrowers, mid-ticket accounts, moderate DPD. Field agents negotiate repayment or set up a structured schedule.
Settlement-first
High DPD, partial recovery likely, borrower shows some willingness. OTS or restructuring offers the best net recovery value.
Legal-first
Secured loans with enforceable collateral, unresponsive borrowers, high outstanding amounts. SARFAESI, DRT, or Lok Adalat depending on ticket size and loan type.
What Is NPA Recovery?
Not every NPA account follows the same path to resolution. Recovery can end in several ways depending on borrower profile, account type, and lender strategy:
- Regularization/Upgrade: If the borrower clears overdue amounts and meets RBI’s prescribed conditions, the account can be upgraded out of NPA status
- Settlement/OTS: The liability is resolved at an agreed amount below the total outstanding and the account is closed
- Legal Recovery: Unresolved accounts may proceed through SARFAESI, DRT, or Lok Adalat depending on loan type and outstanding amount
- Repossession and Disposal: For secured loans where other options are exhausted, collateral may be repossessed and liquidated to recover outstanding dues
Dista Collect supports each of these resolution paths, so collections teams can move accounts toward closure without switching tools or losing visibility.
The NPA Recovery Process: How It Works
A structured NPA recovery process moves through four stages:
Identification and Classification
Accounts are flagged by DPD bucket (SMA-0 through Loss) and routed to the appropriate recovery track based on outstanding amount and collateral.
Borrower Engagement
Field agents, digital channels, and legal teams initiate contact based on account profile, risk tier, and rules usually defined in the strategy builder.
Resolution
The account is closed through repayment, restructuring, OTS, or legal action under SARFAESI or DRT.
Closure and Reporting
Recovery is logged, provisioning is reversed where applicable, and data feeds back into portfolio strategy.
Most lenders lose track of the asset between engagement and resolution due to fragmented data, poor agent routing, and limited real-time visibility.
7 NPA Recovery Strategies That Work
1. Segment Accounts by Recovery Potential
Non-differentiated treatment of NPA accounts wastes effort. An account with recoverable collateral and an account with an untraceable borrower require entirely different approaches.
Effective segmentation uses DPD bucket, outstanding principal, collateral type and value, and borrower repayment history to separate accounts by recovery potential. Teams prioritize high-potential accounts for field visits and legal escalation, while routing lower-priority accounts through digital channels at a lower cost. This reallocation improves recovery rates without adding headcount
Use More Than DPD to Prioritize Accounts
DPD is a starting point, not a complete picture. Two accounts at DPD 90 can have vastly different recovery potential, but treating them the same way wastes both time and effort.
Collections teams should layer additional parameters on top of DPD to build a sharper priority queue:
- Repayment history — Did the borrower pay consistently before slipping, or has the account always been irregular?
- Previous contact outcomes — Has the borrower been reached, refused, or remained unresponsive across prior attempts?
- PTP status — Is there an active promise to pay, and has the borrower honored PTPs in the past?
- Loan type — Secured or unsecured, retail or commercial, each carries different recovery levers
- Proximity — Accounts clustered within a collector’s beat can be prioritized to reduce travel time and increase daily coverage
- Account context — Employment status, co-applicant presence, and guarantor availability all affect recoverability
- Collateral and security — Where applicable, the presence and current value of collateral informs escalation decisions
A field visit, a digital nudge, and a legal notice are not interchangeable. The right action depends on what the full account profile actually says.
2. Use Location Intelligence for Field Agent Routing
Broadly speaking, field recovery is still the primary channel for most banks and NBFCs. However, location-blind routing bleeds cost, leading to a drop in productivity and recovery rates.
Location intelligence solves this by mapping NPA accounts into geographic clusters and building route-efficient beat plans for collectors. Agents cover more cases per day, reach higher-priority borrowers first, and log geo-tagged visit records that supervisors can verify in real time. The result is a more cost-efficient, accountable field operation with a lower cost per recovery.
3. Deploy Omnichannel Borrower Outreach
Borrowers may respond differently, some to a WhatsApp message, others to a call or SMS. Omnichannel outreach lets collectors meet borrowers on the channel they actually engage with, improving contact rates without adding field visits or manual effort.
Digital nudges in early DPD buckets can prevent the need for classification altogether. For accounts already classified, digital outreach reduces the number of expensive field visits required and helps teams identify which borrowers are responsive before deploying agents.
4. Offer Structured Settlement and OTS Options
For deep NPA accounts where full recovery is unlikely, a one-time settlement scheme can recover significantly more than prolonged legal action at a fraction of the cost.
The key is structure. Clear eligibility criteria, defined haircut limits, and timely consults give borrowers a genuine reason to engage. Lenders that run OTS (One Time Settlement) campaigns with transparent terms tend to report better conversion rates than those that negotiate case by case without a framework.
Restructuring vs Settlement/OTS: What Is the Difference?
- Restructuring modifies the repayment terms of an existing loan while the liabiliy remains intact.
- Settlement/OTS resolves the liability at an agreed amount, typically below the total outstanding, and closes the account.
- The two serve different borrower situations and recovery objectives.
- Regulatory classification and accounting treatment differ between the two.
- Lenders should verify current RBI guidelines before deploying either option at scale.
5. Activate SARFAESI and Legal Tools at the Right Time
Statutory recovery tools such as SARFAESI notices, DRT filings, Lok Adalat referrals are powerful, but their value depreciates when initiated too late. Collateral loses value, borrowers transfer assets, and legal timelines stretch further.
Within the bounds set by statute, banks and NBFCs should define clear internal trigger points for legal escalation based on DPD, collateral type, and outstanding amount. SARFAESI works best for secured loans above the eligible threshold. Lok Adalats are effective for smaller retail accounts where speed matters more than recovery quantum. Matching the tool to the account profile improves both recovery rates and legal spend efficiency.
6. Build a Dedicated Recovery Team
Recovery is a specialized function. Teams that handle collections alongside other responsibilities rarely perform as well as those focused exclusively on NPA resolution.
A dedicated recovery team brings expertise in negotiation, legal processes under the RBI Fair Practices Code, and borrower communication. Ongoing training makes a measurable difference in resolution rates. Specialization also enables better performance tracking, since recovery KPIs can be measured cleanly without operational noise from other functions.
7. Track Recovery Metrics in Real Time
You cannot improve what you cannot see. Many lenders still rely on weekly or monthly recovery reports, by which point the window to intervene on a slipping account has often closed.
Real-time dashboards give recovery managers visibility into agent productivity, promise-to-pay (PTP) conversion rates, cost per recovery, and portfolio-level recovery rates by segment. This data closes the feedback loop between field activity and strategy, allowing teams to reallocate effort, escalate accounts, and course-correct without waiting for the next reporting cycle.
The Right Mix Depends on Your Portfolio
No single NPA recovery method works in isolation. The most effective banks and NBFCs combine field force optimization, digital outreach, structured legal escalation, and real-time data calibrated to their portfolio composition, borrower segments, and operational capacity.
The institutions recovering the most aren’t necessarily the ones with the largest teams. They’re the ones with the tightest processes.
Want to see how Dista Collect helps banks and NBFCs build more efficient field recovery operations? Explore Dista Collect.
Frequently Asked Questions About NPA Recovery
Yes. If a borrower clears all overdue amounts and meets RBI's prescribed conditions for upgradation, the lender can reclassify the account out of NPA status. The account must demonstrate satisfactory repayment for the period specified in the applicable RBI circular before the upgrade takes effect. Until that condition is met, the account remains classified even if partial payments resume.
Restructuring modifies the repayment terms of an existing loan — the full liability stays intact and the borrower repays over a revised schedule. A one-time settlement (OTS) resolves the liability at an agreed amount, typically below the total outstanding, and closes the account. The regulatory classification and accounting treatment differ between the two, and lenders should verify current RBI guidelines before deploying either option at scale.
The trigger depends on loan type, outstanding amount, collateral, and borrower response. Secured loans with unresponsive borrowers and enforceable collateral typically move to SARFAESI after standard field and digital collection efforts fail. Accounts above ₹20 lakh may proceed to the Debt Recovery Tribunal. Smaller retail accounts are often referred to Lok Adalats, where resolution is faster and less costly. Lenders should define internal escalation thresholds rather than deciding case by case.
Yes, significantly. Secured loans give lenders access to statutory tools — SARFAESI notices, asset repossession, and DRT filings — that are not available for unsecured accounts. In such a case, BFS organizations usually build compliance checks into recovery workflows.
Unsecured NPA recovery relies primarily on field outreach, digital channels, negotiated settlements, and Lok Adalat referrals. The absence of collateral raises the cost of recovery and reduces the recoverable amount, which makes early intervention more important for unsecured portfolios.
The Insolvency and Bankruptcy Code (IBC) provides a structured framework for restructuring or liquidation in cases of large corporate defaults. It operates through the National Company Law Tribunal (NCLT) and is suited to high-value accounts where other recovery routes have been exhausted. RBI data shows that recovery under the IBC improved to nearly 37% in FY25, even as the number of cases referred for resolution declined. For most retail and MSME.
A write-off removes the loan from a bank's active books and requires full provisioning against the outstanding amount. Writing off a loan frees the capital set aside for provisioning, which the lender can redeploy for fresh lending. Critically, a write-off does not extinguish the borrower's liability — lenders retain the legal right to recover the outstanding amount even after a write-off and may continue field, legal, or ARC-led recovery efforts. Write-offs are a balance sheet tool, not a waiver. shankariasparliamentshankariasparliament
Provisioning is an accounting requirement — lenders set aside a percentage of the outstanding loan amount as a buffer against potential loss, based on the NPA classification bucket (substandard, doubtful, or loss). The RBI prescribes provisioning norms based on the age of the asset as a non-performer. Recovery is the operational effort to collect actual cash from the borrower. Provisioning protects the lender's capital; recovery restores it. Reducing provisioning costs is one of the strongest financial incentives to resolve NPAs faster. outlookmoney
Yes. Banks can sell stressed NPA accounts to Asset Reconstruction Companies (ARCs), which acquire the debt at a discount and manage recovery independently. This gives the originating lender an immediate, clean exit from the stressed asset. ARCs use a combination of restructuring, settlement, and legal tools to recover value from the purchased portfolio. For large or complex NPA accounts where in-house recovery is unlikely to generate sufficient returns, an ARC sale can be a more efficient resolution route than prolonged internal effort.