Choosing the right debt collection software in India has moved from a mere IT decision to a strategic one. With retail delinquencies rising, NPA portfolios growing, and the RBI tightening operational and compliance expectations – banks, NBFCs, and MFIs can no longer afford fragmented collection stacks.
This guide compares the top 7 debt collection and loan recovery software platforms in India. These have been evaluated on the basis of AI capability, field operations, digital outreach, legal workflow automation, and RBI compliance readiness.
Please note – Dista publishes this guide, and Dista Collect is one of the seven platforms. We describe every platform against the same criteria and note where each one is a weaker fit. Capabilities reflect how each vendor describes its product, so confirm details in a demo.
Why choosing the right debt collection software matters in India in 2026
The RBI’s June 2026 Financial Stability Report put bank gross NPAs at 1.8% at the end of March 2026, a multi-decade low. While overall asset quality is strong, the stress sits in specific segments.
Non-housing retail loans made up 58.4% of household borrowings, and gross NPAs on unsecured retail loans (1.7%) were more than double those on secured retail loans (0.7%), according to Policy Circle’s summary of the report. Fintech lenders carry more of the risk. Unsecured loans made up 70.5% of their portfolios, with nearly half going to borrowers under 35, per Kotak Neo.
Defaults on small-ticket personal loans at fintech firms rose to 6.4% in March 2026 from a little over 4% in March 2024, according to a summary of The Hindu’s report.
Conduct rules are tightening too. In August 2026, the RBI issued a comprehensive loan recovery framework for commercial banks that takes effect on January 1, 2027. It tightens rules for recovery agents, requires a comprehensive recovery policy and grievance redressal mechanisms, and sets safeguards for technology-based recovery tools.
For collection heads, these facts point to four gaps to look for in any platform:
- No single source of truth across field agents, telecallers, agencies, and legal teams.
- Siloed CRMs, standalone tracking apps, and disconnected telecalling tools.
- Delayed action on delinquent accounts because of weak risk-based case prioritization.
- Compliance gaps in borrower communication audit trails, contact-hour and DND controls, and SARFAESI documentation.
What is debt collection software?
Debt collection software helps lenders manage recovery from early reminders through legal action and settlement. Vendors also call this category debt collection and recovery software or collection management software for NBFCs and banks.
Narrower tools, often called collections products, focus on agent workflows and early-stage engagement. Full-lifecycle collections platforms cover every stage from pre-delinquency to repossession and disposal. Vendors use these terms loosely, so do verify what each product actually covers.
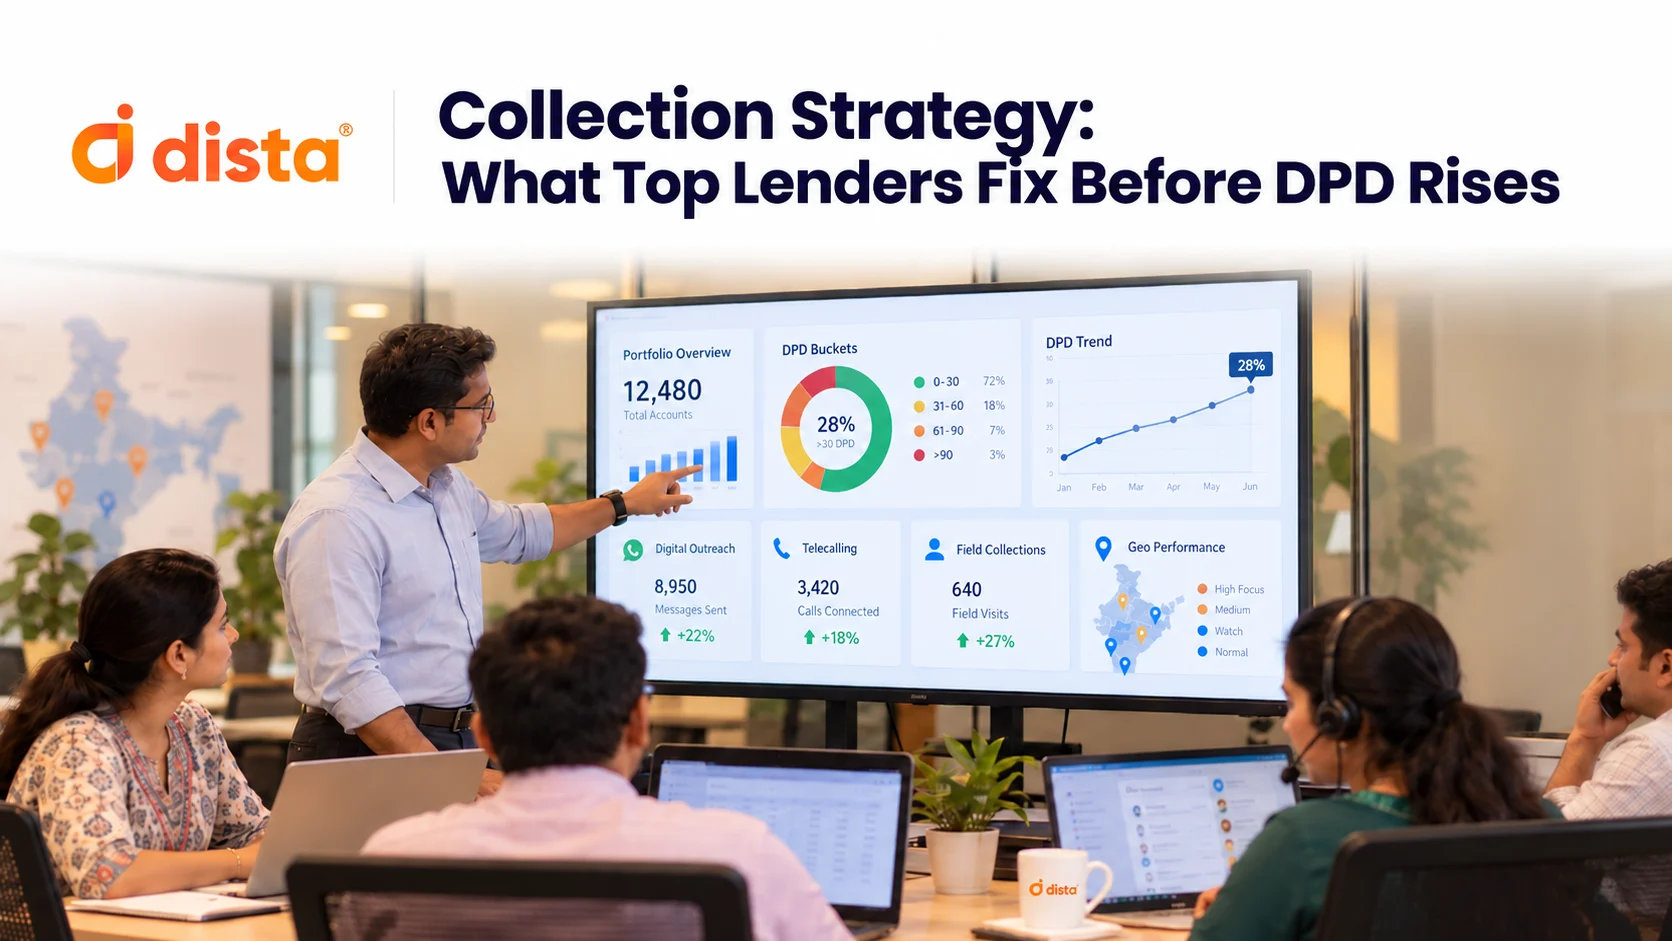
Also Read – Collection Strategy: What Top Lenders Fix Before DPD Rises
How we evaluated the platforms
We described each platform against five criteria:
- AI capability: Case prioritization, allocation, and repayment prediction.
- Field operations: Routing, audit compliance, mobile apps, and receipting.
- Digital outreach: WhatsApp, SMS, IVR, email, and payment links.
- Legal workflow automation: SARFAESI, Section 138, and arbitration tracking.
- Compliance support: Audit trails, communication controls, and documentation.
Please note – As of the time of writing this blog, RBI regulates lenders, not software vendors, so compliance obligations stay with the lender. We list features that help lenders document and control compliance, and we do not treat any platform as RBI approved. Where a vendor’s materials did not describe compliance features, the table says to confirm with the vendor.
This guide does not list prices. Ask each vendor for a quote and use the cost checklist in Step 6 below.
Software | Best for | Key strength | Compliance support (vendor-described) | Not ideal for |
Dista Collect | Mid-sized to large banks and NBFCs | Unified Collections, AI plus location intelligence | Audit trails and documentation workflows for regulatory reporting | Lenders that only need legal case tracking or basic reminders |
Credgenics | Banks, NBFCs, ARCs, fintechs | Legal and digital-first recovery | SARFAESI, Section 138, and arbitration tracking with notice generation | Lenders prioritizing full-lifecycle field operations |
FinnOne Neo Collections | Large banks and NBFCs with legacy or on-premise needs | 80+ APIs and enterprise configurability | Workflow modules for SARFAESI, Section 138, and repossession | Lenders prioritizing AI or location intelligence over legacy compatibility |
LeadSquared | Early-stage collections | CRM plus field agent productivity | Confirm with vendor | Lenders with heavy mid-stage or legal workloads |
Vymo CollectIQ | High-volume field operations | Guided workflows and incentive management | Confirm with vendor | Small or low-volume field teams |
Mobicule | Telecom, BFSI, utilities | Modular, integration-ready | Audit features for telecom, utilities, and BFSI regulatory environments | Lenders wanting a product built only for lending |
goCollect (Credility) | Field-intensive NBFCs and MFIs | Smart auto-allocation and UPI receipts | Confirm with vendor | Large banks (positioned for NBFCs and MFIs) |
The Top 7 Platforms Compared
1. Dista Collect

Dista Collect is an AI/GenAI-powered, location-first, unified debt collection CRM, purpose-built for Indian banks and NBFCs. It brings together the power of AI in designing omnichannel recovery strategies. It unifies all stages of debt collections including settlement, repossession and disposal with a compliance-ready framework, giving lenders complete visibility and control across every bucket, every team, and every channel.
With Dista, leading BFS organizations have achieved,
- 30% Higher Collection Rate
- 25% Higher True Visits
- 100% Automation in Case Allocation
Why Choose Dista Collect?
- Unified Collections & Customer 360: Dista Collect pulls data from your LMS and Data Lakes into one view, so teams see every loan and interaction for a borrower in a single place.
- GenAI Strategy & Dynamic Case Allocation: Managers build collection strategies without code, and the platform assigns each case to an agent based on location and the rules you set.
- Field Force Operations & Location Intelligence: Collectors get optimized routes, GPS-verified visits, and a mobile app that keeps their daily work in one place.
- Telecalling & Digital Engagement: Telecallers work from an integrated telephony view of each customer, while AI analyzes voice sentiment to guide the conversation.
- Cash Recovery, Receipting & Payment Reconciliation: Collectors record and receipt cash receipt at the doorstep, and the system matches those payments to loan accounts automatically.
- Settlement & Repossession Management: Teams apply rule-based settlement matrices and follow RBI-compliant repossession workflows from the first notice to the final recovery step.
- Analytics, Productivity & Gamification: Dashboards track agent and portfolio performance, and incentives and smart nudges keep collectors focused on their targets.|
Best For: Mid-sized to large Banks, NBFCs and NBFC-MFIs that need a comprehensive, AI-driven, location-powered, and audit-ready platform.
2. Credgenics
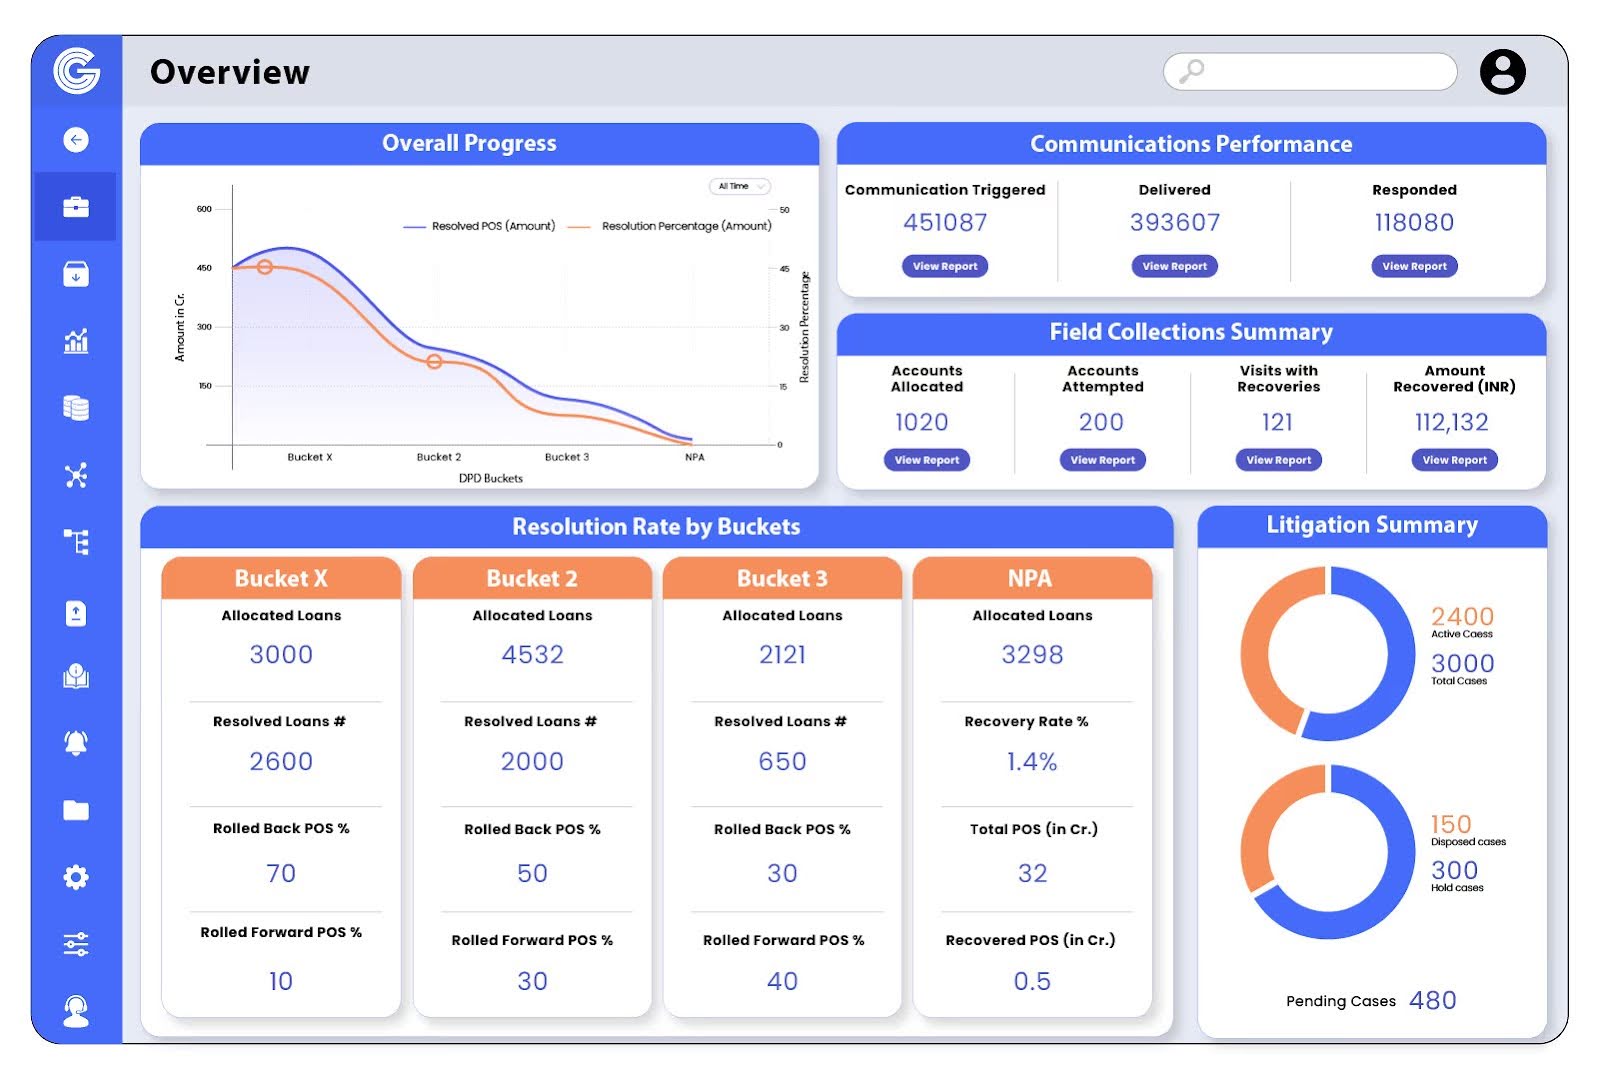
Credgenics is a SaaS platform for banks, NBFCs, MFIs, and fintechs across the collections lifecycle. Its main strength is legal recovery: SARFAESI case management, Section 138 litigation tracking, and advocate performance monitoring. That focus suits lenders with heavy legal escalation or ARC portfolio management needs.
Key capabilities:
- Legal workflow automation: Tracks Section 138, arbitration, and SARFAESI cases, including hearing reminders, notice generation, and advocate performance monitoring.
- Omnichannel digital outreach: Automates borrower outreach, including voicebot calling and cloud-based auto and predictive dialers, with analytics on communication and channel effectiveness.
- AI and analytics: Machine learning models evaluate communication and channel effectiveness, and collections analytics support strategy decisions.
- CG Collect field app: A multilingual mobile app with geo-tracking, map navigation, and digital payments. Credgenics also acquired Arrise to expand its field collections capabilities.
Best for: BFSI organizations where legal escalation management and digital-first outreach are the main priorities.
3. FinnOne Neo Collections (Nucleus Software)
FinnOne Neo Collections is a configurable, workflow-driven debt recovery platform. Institutions use it largely for its ability to integrate with complex core banking environments and legacy infrastructure that newer platforms may not support. It is most relevant where compatibility with existing systems is the dominant procurement constraint.
Key capabilities:
- Integration ecosystem: 80+ APIs connect core banking systems (including Finacle), LOS, LMS, and third-party services.
- Enterprise configurability: Supports classification queues, champion-challenger strategies, rule-engine-driven scripts, and configurable allocation across agent types.
- Pre-delinquency and delinquency coverage: Manages early-warning outreach and full delinquency workflows in one platform.
- Legal and repossession modules: Workflow-driven modules cover SARFAESI, Section 138 litigation, repossession, asset sale, and settlements.
- mCollect field app: Enables UPI, AEPS, debit card, and cash collections on mobile with real-time sync and geo-tracking.
Best for: Institutions where legacy system integration and enterprise configurability are the primary constraints.
4. LeadSquared Collections CRM
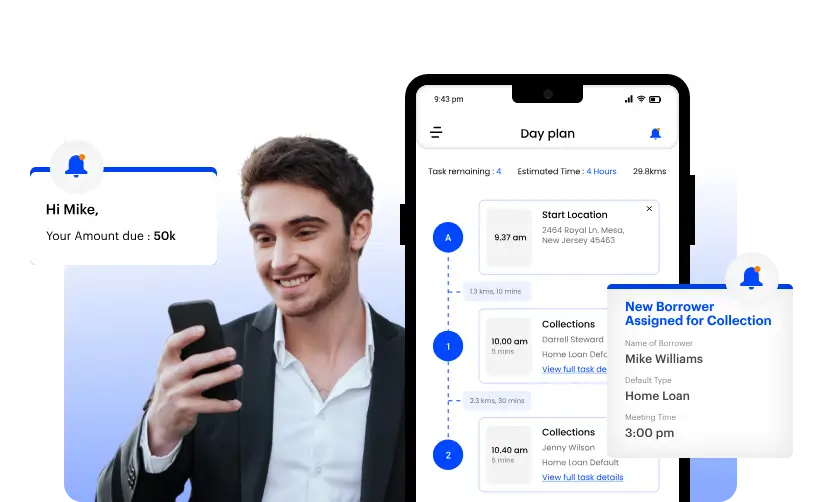
LeadSquared offers a collections platform for NBFCs that sits on top of an existing loan management system and brings calling, field, legal, settlement, and repossession workflows into one system. It also includes hard bucket workflows, settlement and foreclosure handling, automated recovery workflows, real-time field tracking, and day-planning tools. Agents plan daily routes, and managers see performance live. LeadSquared states that the platform complies with RBI guidelines and the DPDP Act 2023, so confirm the scope in a demo.
Key capabilities:
- Role-based visibility: Role-wise dashboards and day-wise calling and field activity reports for each level of the collections hierarchy.
- Mobile-first task management: Structured daily workflows for on-ground collection agents.
- Automated outreach: Sends payment reminders by WhatsApp, SMS, and voice, with promise-to-pay management and follow-up automation.
Best for: NBFCs that want calling, field, legal, and settlement workflows on a CRM foundation that sits on top of their existing loan management system.
5. Vymo CollectIQ
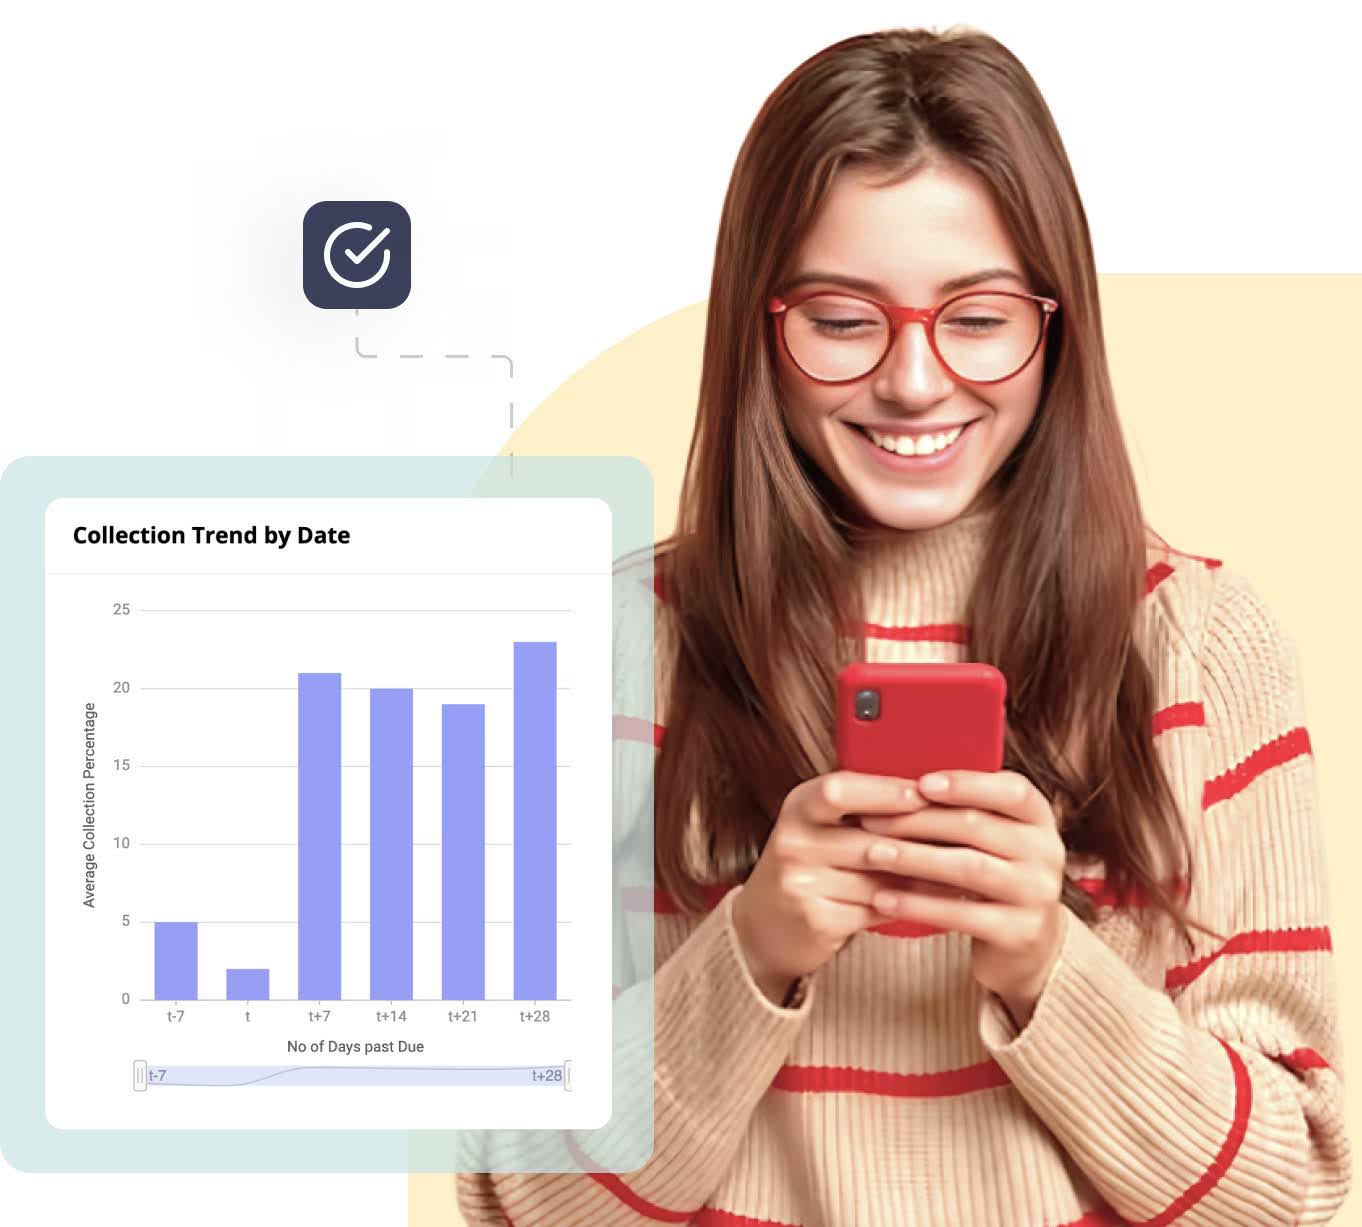
Vymo CollectIQ is a mobile-first, AI-powered debt collections platform for banks and NBFCs from Vymo, a sales engagement vendor. It brings case allocation, agent tracking, customer engagement, and payment workflows into one view, and it integrates with LMS, CRM, and payment gateway systems.
Key capabilities:
- Mobile-first design: Built for the debt recovery challenges of lenders in India and Asia.
- AI risk scoring: An AI engine analyzes customer data and assigns a dynamic risk score to support risk-based case allocation.
- Escalation management and live dashboards: Automates escalations and gives leadership a live view of the portfolio.
Best for: Banks and NBFCs that want an AI-driven, mobile-first platform integrated with their LMS, CRM, and payment gateways.
6. Mobicule
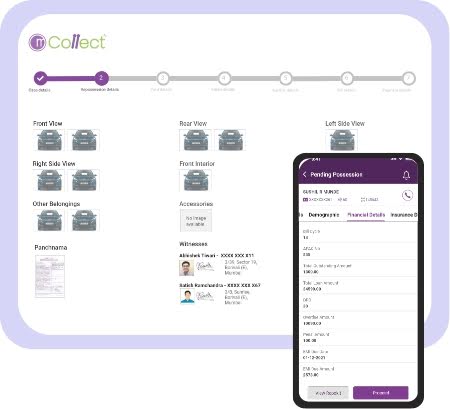
Mobicule offers mCollect, a debt collection platform built on a phygital model that blends digital outreach, a human contact center, and field presence. Mobicule describes the platform as covering the collection journey from first contact through legal escalation for BFSI and telecom clients. The company launched a repossession module in January 2023 and the full mCollect platform in October 2023.
Key capabilities:
- Phygital model: Combines digital nudges, contact center calling, and field collections.
- Repossession module: Maps the processes involved in repossessing an asset as part of the recovery product.
- Field-force heritage: Mobicule started in mobile field force technology and has deployed it across sales and distribution, telecom, and BFSI.
Best For: Enterprises in telecom, utilities, and BFSI that need a modular, compliance-ready, and integration-friendly collections platform.
7. goCollect (Credility)
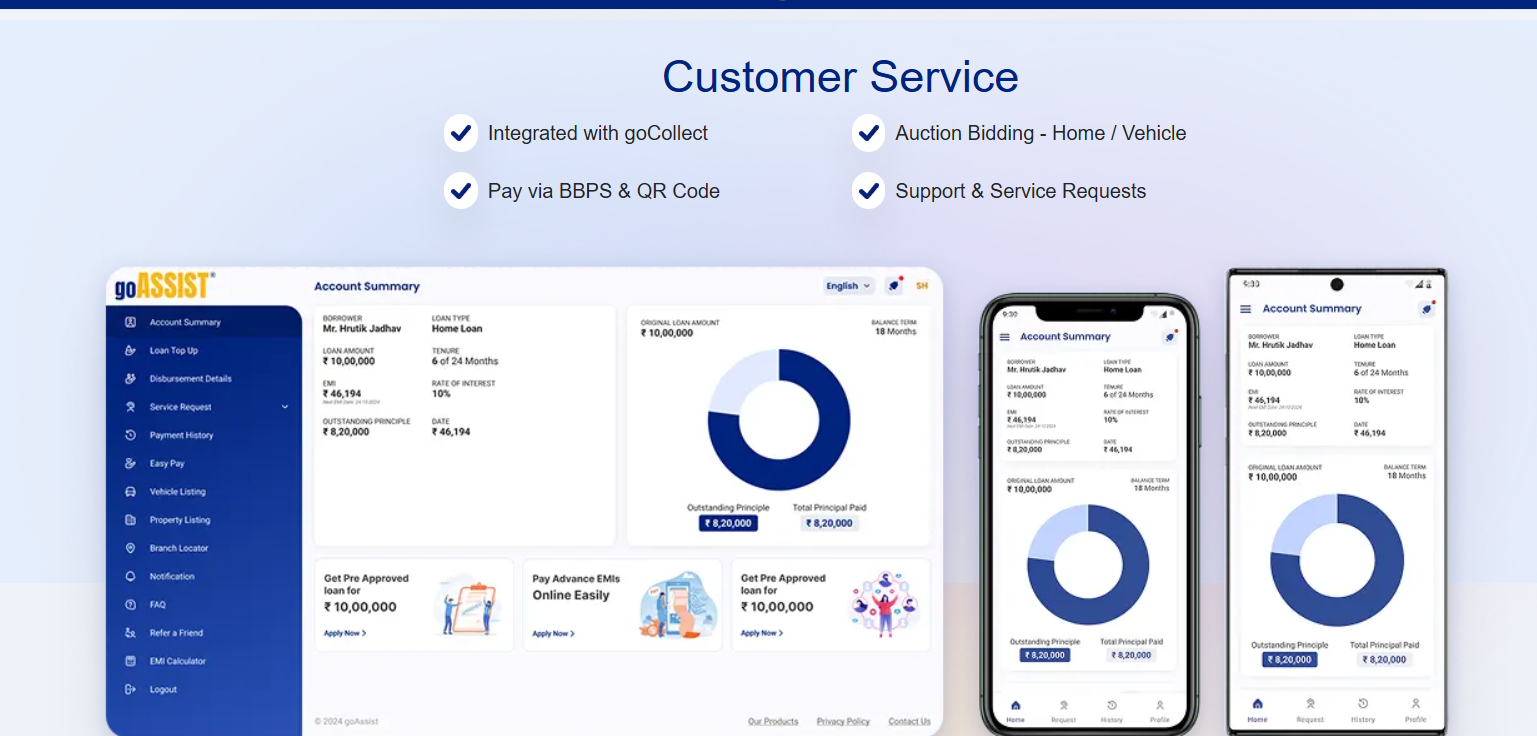
goCollect by Credility is a loan collection platform used by housing finance companies, NBFCs, microfinance institutions, and banks. It provides automated case allocation, tele-collection, multichannel digital reminders, and field collection management.
Key capabilities:
- Automated allocation: assigns cases automatically and supports hierarchical business structures.
- Multichannel reminders and tele-collection: supports digital reminders and a dedicated tele-collection function.
- Waiver and settlement processing: handles waivers and settlements within the collections workflow.
- AI-driven analytics: includes risk profiling, early warning signals, payment prediction, and collection strategy optimization.
Best for: NBFCs, MFIs, and housing finance companies that want automated allocation with field and tele-collection management in one system.
India-specific Compliance Features
Use this checklist when you evaluate any platform:
- SARFAESI case management and documentation
- Section 138 (NI Act) litigation tracking
- NACH mandate management
- Communication controls for DND status, contact frequency, and permitted contact hours (the RBI has barred recovery calls before 8 a.m. and after 7 p.m.)
- Audit trails for every borrower interaction
- Data masking in line with applicable privacy laws
- OTP-based payment verification
- Grievance officer contact details in recovery communications, which the new framework for commercial banks requires
These features support compliance. They do not replace your compliance team’s review of the directions that apply to your institution.
A Must-Have Checklist to help you evaluate vendors on the basis of compliance and regulatory needs.
Why BFS Enterprises Are Replacing Legacy Systems in 2026
- No single source of truth across field agents, telecallers, agencies, and legal teams
- Operational inefficiencies driven by siloed CRMs, standalone tracking apps, and disconnected telecalling tools
- Delayed action on delinquent accounts due to poor risk-based case prioritization
- Compliance gaps in borrower communication audit trails, DND controls, and SARFAESI documentation
How to Choose the Right Debt Collection Software for Your Organization
Selecting a debt recovery solution is not a feature checklist exercise. Here is a decision-ready framework built around your specific lending profile.
Step 1: Segment by Lender Type First
Different institution types have fundamentally different collection challenges:
- Large Banks & Enterprise NBFCs: Need AI-driven prioritization, end-to-end lifecycle management, geo-based field operations, and complete portfolio visibility. Dista Collect is the strongest fit, with FinnOne Neo as an alternative for institutions where deep legacy system integration is the binding constraint
- Mid-Sized NBFCs: Need intelligent case allocation, DPD workflow automation, and real-time field coordination. Dista Collect and Credgenics are the leading options
- MFIs & Smaller NBFCs: Need mobile-first, lightweight platforms with smart allocation and real-time receipt. For larger MFI networks with more complex portfolio structures, Dista Collect is worth evaluating
Step 2: Match Software to Your Collections Stage
- Bucket 0–1 (Early Stage): Prioritize automated digital outreach, DND-compliant communications, and mobile-first agent workflows
- Bucket 2–3 (Mid Stage): Look for AI-driven case prioritization, geo-routing, field force optimization, and PTP tracking
- NPA / Legal / Written-Off: Require SARFAESI case management, Section 138 litigation tracking, hearing dashboards, and audit-ready documentation
Step 3: Evaluate Execution Intelligence, Not Just Dashboards
The best platforms go beyond reporting. Look for systems that intelligently prioritize cases based on risk score, DPD bucket, geography, and agent skill — not just ones that surface data after the fact.
Step 4: Verify Integration & Compliance Readiness
Your collection software must integrate with your LMS for real-time data sync. For Indian lenders, RBI-compliant audit trails, NACH mandate management, and DND-adherent communication controls are non-negotiable — not nice-to-have features.
Step 5: Run a Pilot on a Representative Portfolio
Before full deployment, test on a meaningful segment. Track:
- Change in case closures week-on-week
- Increase in true visits per agent
- Reduction in time-to-contact for fresh delinquencies
- Compliance audit pass rates
Step 6: Calculate Total Cost of Ownership (TCO)
Look beyond licensing fees. Factor in integration costs, implementation timelines, training, support SLAs, and the hidden cost of not using automated debt collection software.
Frequently Asked Questions: Debt Collection Software in India
Q: What is debt collection software?
Debt collection software is a digital platform that helps banks, NBFCs, MFIs, and ARCs manage the end-to-end loan recovery process — including borrower communication, field agent management, case prioritization, legal workflows, and RBI compliance tracking.
Q: Which is the best debt collection software in India in 2026?
For banks and NBFCs seeking a comprehensive, AI-driven, and location-intelligent platform that covers the full collections lifecycle, Dista Collect is the strongest fit. Credgenics is the specialist choice for legal escalation and ARC operations. FinnOne Neo suits institutions where legacy system integration is the primary constraint. The right choice ultimately depends on your lender type, collections stage, and portfolio complexity.
Q: What India-specific compliance features should debt collection software support?
Key India-specific compliance features include: SARFAESI case management, Section 138 (NI Act) litigation tracking, NACH mandate management, RBI-compliant DND and communication frequency controls, data masking per privacy laws, audit trails for all borrower interactions, and real-time OTP-based payment verification.
Q: How does AI improve debt collection in India?
AI improves debt collection by intelligently segmenting borrower risk, predicting repayment likelihood, auto-prioritizing cases for field agents, optimizing geo-based collection routes, and triggering personalized multilingual communications — all of which increase recovery rates while reducing the cost-to-collect.
Q: What is the difference between a debt collection CRM and a full-lifecycle collections platform?
A debt collection CRM (like LeadSquared) focuses primarily on agent workflow management, task structuring, and early-stage borrower engagement. A full-lifecycle collections platform (like Dista Collect) manages the entire recovery journey — from Bucket 0 digital outreach through field operations, agency coordination, repossession, legal escalation, and NPA management — in a single integrated system.
Final Verdict
The debt collection software landscape in India has matured significantly — and the gap between platforms built specifically for Indian lending operations and generic global tools has never been wider.
For banks and NBFCs — mid-sized to large — seeking a truly unified, AI-driven, location-intelligent platform that covers the full collections lifecycle, Dista Collect is the most comprehensive solution available today. Its combination of SPACE-based AI allocation, geo-powered field operations, end-to-end DPD lifecycle management, and a single-pane visibility layer addresses the structural fragmentation that most Indian lenders still struggle with.
The right choice depends on your lender type, collections stage, portfolio complexity, and where your biggest operational gaps currently sit.
Ready to see Dista Collect in action?
Book a demo to see how AI + Location Intelligence transforms field collections, true visit rates, and recovery outcomes for Indian lenders.
Note – All images have been sourced from the official webpages of the concerned companies.